Debt Consolidation Guidance

Debt Consolidation Guidance

One payment can mean different things. We help you understand the difference.

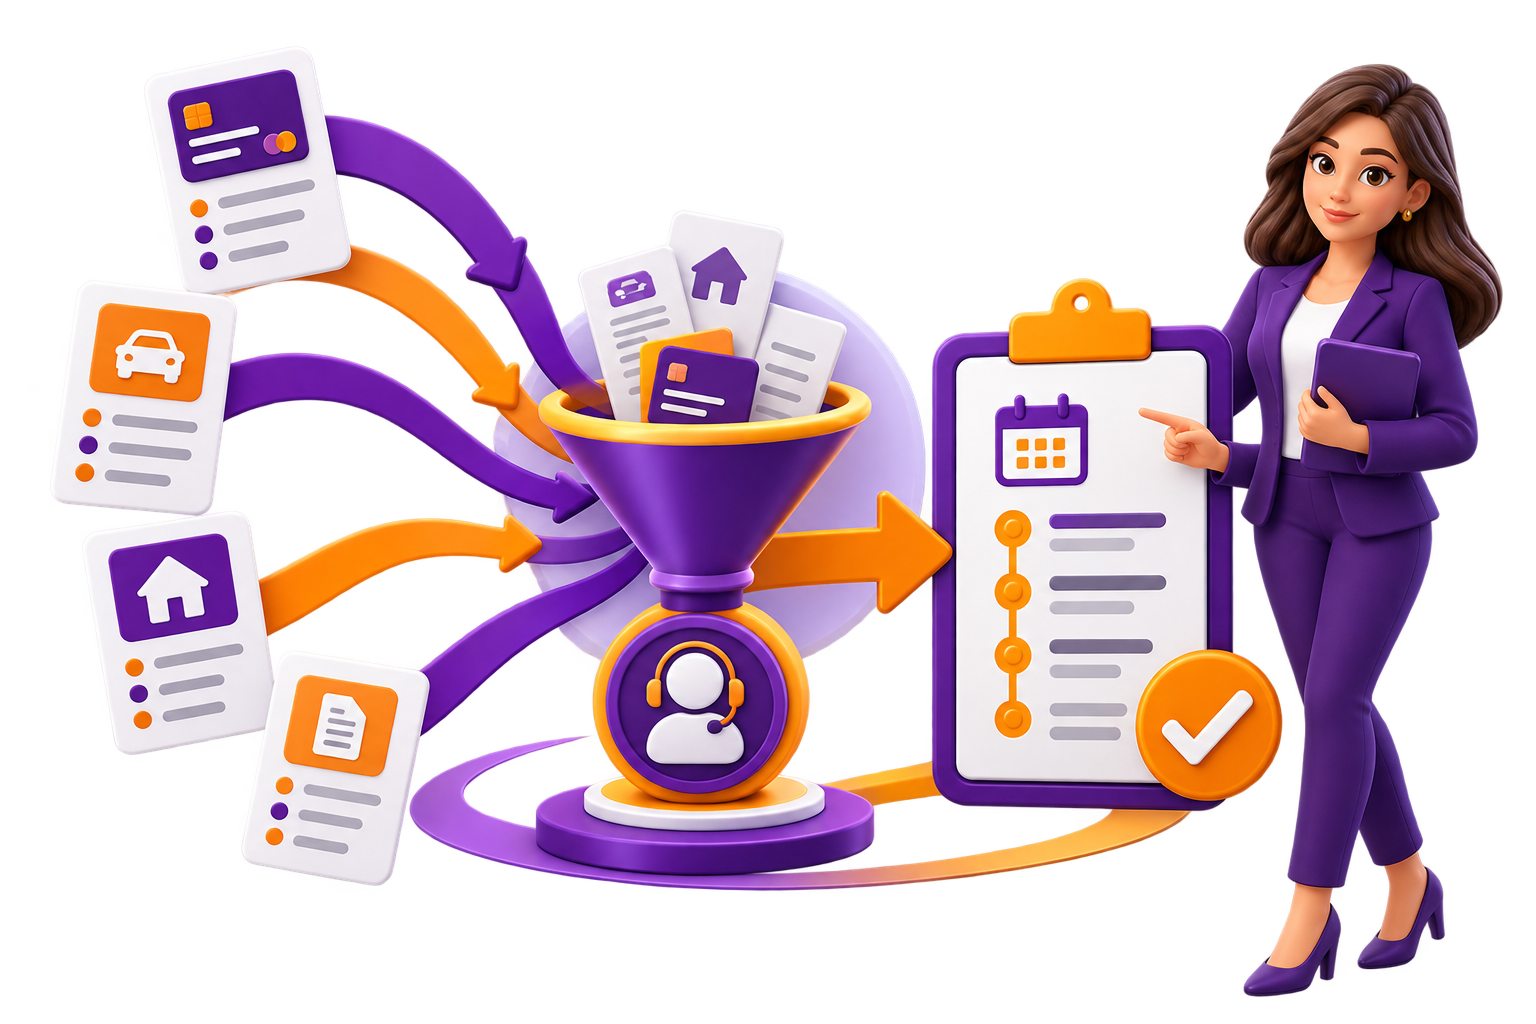
The term “debt consolidation” is commonly used for two different solutions. A consolidation loan is new credit used to settle several accounts. Consolidation through debt counselling is not a new loan; qualifying debts are dealt with through a structured repayment arrangement and payments are normally distributed to creditors through the applicable channel.

Debt consolidation guidance

Understand the two different routes

A consolidation loan and debt counselling can both result in a simpler monthly payment, but they work differently and have different requirements.

Consolidation loan

A new credit agreement with a registered lender

  • Requires an application to a registered credit provider and an affordability assessment.
  • May simplify several accounts into one new loan repayment.
  • May reduce or increase the total cost, depending on the rate, fees and repayment term.
  • Is generally difficult to obtain when a consumer is already over-indebted or has a poor credit profile.

Debt counselling

A formal single-payment solution for qualifying consumers

  • Does not give the consumer additional borrowed money.
  • Uses a formal debt-counselling process for qualifying over-indebted consumers.
  • Creates a proposed affordable repayment structure based on the consumer’s circumstances.
  • Restricts access to new credit while the debt-review status is active.